
 Kontakt
 Jak nakupovat

Doručení
Nákupní rádce
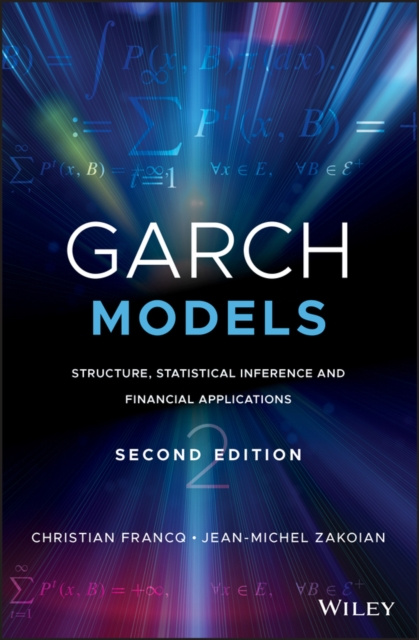
GARCH Models
 Angličtina
 330 b
Zákazníci také koupili


 /
 Adobe ePub DRM
 702
Kč


Provides a comprehensive and updated study of GARCH models and their applications in finance, covering new developments in the discipline This book provides a comprehensive and systematic approach to understanding GARCH time series models and their applications whilst presenting the most advanced results concerning the theory and practical aspects of GARCH. The probability structure of standard GARCH models is studied in detail as well as statistical inference such as identification, estimation, and tests. The book also provides new coverage of several extensions such as multivariate models, looks at financial applications, and explores the very validation of the models used. GARCH Models: Structure, Statistical Inference and Financial Applications, 2nd Edition features a new chapter on Parameter-Driven Volatility Models, which covers Stochastic Volatility Models and Markov Switching Volatility Models. A second new chapter titled Alternative Models for the Conditional Variance contains a section on Stochastic Recurrence Equations and additional material on EGARCH, Log-GARCH, GAS, MIDAS, and intraday volatility models, among others. The book is also updated with a more complete discussion of multivariate GARCH; a new section on Cholesky GARCH; a larger emphasis on the inference of multivariate GARCH models; a new set of corrected problems available online; and an up-to-date list of references. Features up-to-date coverage of the current research in the probability, statistics, and econometric theory of GARCH models Covers significant developments in the field, especially in multivariate models Contains completely renewed chapters with new topics and results Handles both theoretical and applied aspects Applies to researchers in different fields (time series, econometrics, finance) Includes numerous illustrations and applications to real financial series Presents a large collection of exercises with corrections Supplemented by a supporting website featuring R codes, Fortran programs, data sets and Problems with corrections GARCH Models, 2nd Edition is an authoritative, state-of-the-art reference that is ideal for graduate students, researchers, and practitioners in business and finance seeking to broaden their skills of understanding of econometric time series models.


Informace o knize
Angličtina
Kategorie

Darujte tuto knihu ještě dnes
Je to snadné
1 Přidejte knihu do košíku a zvolte doručit jako dárek 2 Obratem vám zašleme poukaz 3 Kniha dorazí na adresu obdarovanéhoMohlo by vás také zajímat
 /
 Pevná
2 598
Kč


 /
Brožovaná
732
Kč
 /
Brožovaná
389
Kč
 /
Brožovaná
1 203
Kč

Ahoj! Jsem Libroamiko, tvůj knižní rádce.
Jak ti můžu pomoct?