
 Kontakt
 Jak nakupovat

Doručení
Nákupní rádce
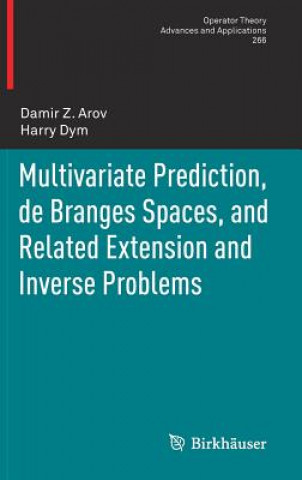
Multivariate Prediction, de Branges Spaces, and Related Extension and Inverse Problems
 Angličtina
 259 b
Až 30 dní na vrácení zboží
Zákazníci také koupili








 /
 Brožovaná
 1 620
Kč


 /
Brožovaná
994
Kč


This monograph deals primarily with the prediction of vector valued stochastic processes that are either weakly stationary, or have weakly stationary increments, from fi nite segments of their past. The main focus is on the analytic counterpart of these problems, which amounts to computing projections onto subspaces of a Hilbert space of p x 1 vector valued functions with an inner product that is de fined in terms of the p x p matrix valued spectral density of the process. The strategy is to identify these subspaces as vector valued de Branges spaces and then to express projections in terms of the reproducing kernels of these spaces and/or in terms of a generalized Fourier transform that is obtained from the solution of an associated inverse spectral problem. Subsequently, the projection of the past onto the future and the future onto the past is interpreted in terms of the range of appropriately defi ned Hankel operators and their adjoints, and, in the last ch 1.


Informace o knize
Angličtina

Darujte tuto knihu ještě dnes
Je to snadné
1 Přidejte knihu do košíku a zvolte doručit jako dárek 2 Obratem vám zašleme poukaz 3 Kniha dorazí na adresu obdarovanéhoMohlo by vás také zajímat


 /
Brožovaná
564
Kč




 /
Pevná
926
Kč

 /
Brožovaná
206
Kč

 /
Brožovaná
243
Kč
 /
Brožovaná
815
Kč
Ahoj! Jsem Libroamiko, tvůj knižní rádce.
Jak ti můžu pomoct?